[From Rick Marken (2004.04.04.2200 PDT)]
Here are some more data on the temporal relationship between investment
and growth. Thanks to a post some time ago from Bill Williams I was
able to get yearly data on investment and growth from 1929 to 1946.
Quarterly data isn't available until 1947.
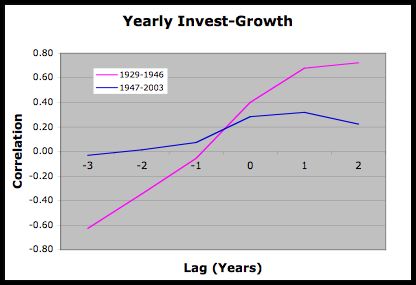
The relationship between total investment (government and private) and
growth for different yearly lags is shown separately for the years
1929-1946 and 1947-2003. Negative lag (on the x axis of the graphs) is
the number of years by which investment precedes growth; positive lag
is the number of years by which investment follows growth. In both
1929-1946 and 1947-2003, there is a weak or negative relationship
between investment and growth when investment precedes growth. The
relationship becomes positive when investment follows growth,
suggesting that it is the expectation of future growth that leads to
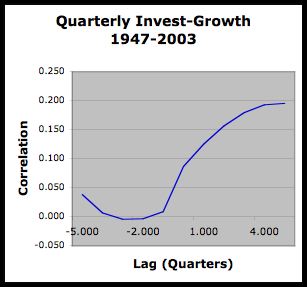
increases in current investment. This relationship between investment
and growth is clearer in the quarterly data, which is only available
for the years 1947-2003. The yearly investment versus growth plots are
presented just to show that the relationship between overall investment
and growth was apparently about the same in the depression and
post-depression era (1929-1946) as it was in more "normal" times
(1947-2003).
What would really be nice to see is the yearly (or, better, quarterly)
growth and investment data starting in, say, 1900. Does anyone know if
that data is available on the net?
Best
Rick
Richard S. Marken
marken@mindreadings.com
Home 310 474-0313
Cell 310 729-1400
[From David Goldstein (2004.04.05.0518 EDT)]
[Rick Marken (2004.04.04.2200 PDT)]
Rick,
Any thoughts about why the relationship seems stronger for the earlier
years?
In the earlier years, the relationship approaches a correlation of .60 which
is as strong as between IQ and educational achievement.
David
David M. Goldstein, Ph.D.
···
----- Original Message -----
From: "Rick Marken" <marken@MINDREADINGS.COM>
To: <CSGNET@listserv.uiuc.edu>
Sent: Monday, April 05, 2004 1:04 AM
Subject: Investment and Growth
[From Rick Marken (2004.04.04.2200 PDT)]
Here are some more data on the temporal relationship between investment
and growth. Thanks to a post some time ago from Bill Williams I was
able to get yearly data on investment and growth from 1929 to 1946.
Quarterly data isn't available until 1947.
The relationship between total investment (government and private) and
growth for different yearly lags is shown separately for the years
1929-1946 and 1947-2003. Negative lag (on the x axis of the graphs) is
the number of years by which investment precedes growth; positive lag
is the number of years by which investment follows growth. In both
1929-1946 and 1947-2003, there is a weak or negative relationship
between investment and growth when investment precedes growth. The
relationship becomes positive when investment follows growth,
suggesting that it is the expectation of future growth that leads to
increases in current investment. This relationship between investment
and growth is clearer in the quarterly data, which is only available
for the years 1947-2003. The yearly investment versus growth plots are
presented just to show that the relationship between overall investment
and growth was apparently about the same in the depression and
post-depression era (1929-1946) as it was in more "normal" times
(1947-2003).
What would really be nice to see is the yearly (or, better, quarterly)
growth and investment data starting in, say, 1900. Does anyone know if
that data is available on the net?
Best
Rick
----------------------------------------------------------------------------
----
----------------------------------------------------------------------------
----
----------------------------------------------------------------------------
----
Richard S. Marken
marken@mindreadings.com
Home 310 474-0313
Cell 310 729-1400
[From Bill Powers (2004.04.05.0810 MST)]
Rick Marken (2004.04.04.2200 PDT)--
Just for kicks, how about doing the correlations between investment and
lagged investment, and between growth and lagged growth?
Best,
Bill P.
[From Rick Marken (2004.04.05.0920)]
David Goldstein (2004.04.05.0518 EDT)--
Any thoughts about why the relationship seems stronger for the earlier
years?
I think it may be a result of the fact that there are a smaller number of
points during that period. I've found that the yearly data don't really
give a good picture of what's going on in terms of the relationship between
investment and growth anyway (at least in the US) because the investment
decisions (which seem to be based on perceived growth or some variable
related to growth) seem to be made within months of the increase or decrease
in growth. So the yearly data are kind of useless. That's really unfortunate
because it would be very interesting to look at the quarterly data for the
period 1920 to 1930 (data which are apparently unavailable). Odd things do
seem to be going on in that period (at least at the yearly level) in terms
of investment and growth. But I think the quarterly relationship between
investment and growth should still look basically like the relationship seen
in the 1947-2003 era. But maybe not. It's possible that there really was
general effort on the part of producers to invest in order to grow, without
consideration of the existence of demand for the product of that investment.
Maybe that's what led to all the trouble.
Bill Powers (2004.04.05.0810 MST)
Just for kicks, how about doing the correlations between investment and
lagged investment, and between growth and lagged growth?
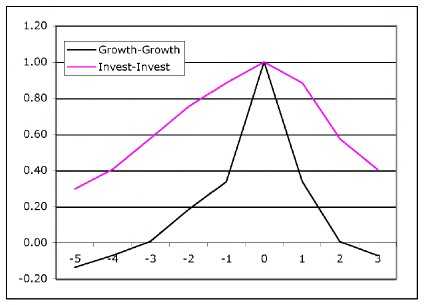
I don't have the yearly 1929-1946 data or the quarterly 1947-2003 data here
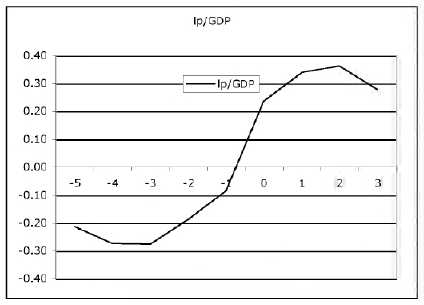
at work. But I do have the quarterly US 1953-2003 data. So I computed the
lagged auto-correlations for private investment and growth. The results are
shown in the AutoCorr.jpg graph below. For comparison I show the lagged
correlation between private investment and growth.
I don't know what to make of the lagged autocorrelations. The growth curve
is negatively correlated with itself at negative lags greater than 3
quarters. But it is also negatively related to itself at positive lags
greater than 2 quarters. The lagged auto-correlation curves don't look
anything like the lagged growth investment curve which is based on these two
data series.
But there it is.
Best regards
Rick
···
--
Richard S. Marken
MindReadings.com
Home: 310 474 0313
Cell: 310 729 1400
[From Bill Powers (2004.04.05.1135 MST)]
Rick Marken (2004.04.05.0920) --
I don't know what to make of the lagged autocorrelations. The growth curve
is negatively correlated with itself at negative lags greater than 3
quarters. But it is also negatively related to itself at positive lags
greater than 2 quarters. The lagged auto-correlation curves don't look
anything like the lagged growth investment curve which is based on these two
data series.
I think the conclusions we can draw about these phenomena is similar to
what can be said about most proposed social laws of behavior: SOME DO AND
SOME DON'T,
With the correlations obtainable from these data, we can be pretty sure
that sometimes investment precedes growth, and sometimes, perhaps slightly
more often, it follows growth. This fits a general pattern in which
sometimes entrepreneurs make a large investment to get a new company off
the ground, with increased business following fairly quickly, and
sometimes, perhaps even more often, other entrepreneurs see a good thing
starting up and hurry to get their own investment money together so they
can also get into the new business that has already started.
The correlations are low enough that we have to say these are just bare
suggestions of a relationship superimposed on a random noise level several
times larger than the observed effect. It would not be possible to predict
whether a given investment was going to lead to an increase in business
activity, or an increase in business activity was going to lead to an
increase in investment -- though after observing a large number of events,
we could conclude that the latter is slightly more probable than the
former. If I didn't consider any of my own money to be surplus to
requirements, I wouldn't make a bet either way.
We need to look for more striking correlations if the data are to be of any
use for testing models. For example, in Econ005, I assume that the typical
plant has a manager (or equivalent) who adjusts prices to keep inventory
constant. It would be interesting to know whether any data are available
concerning inventories and prices. The assumed manager causes prices to
fall when inventories rise, and vice versa. I know this is pretty obvious,
but is there any corroboration of this assumption in available data?
Best,
Bill P.
[From Rick Marken (2004.04.05.1330)]
Bill Powers (2004.04.05.1135 MST)]
We need to look for more striking correlations if the data are to be of any
use for testing models.
I don't think the correlations are what we would use to test the models. I
would test the economic models by looking at the correlation between model
behavior and the behavior of real world economic variables that correspond
to model variables. The only thing that is interesting to me about the
lagged correlations between investment and growth is that they are the
opposite of what one would expect based on the assumption that, on average,
increased investment leads to increased growth. The correlations don't say
anything about how investment and growth _are_ related but I think they are
clearly inconsistent with the simple assumption that investment, on average,
leads to growth.
Best
Rick
···
--
Richard S. Marken
MindReadings.com
Home: 310 474 0313
Cell: 310 729 1400
[From Bill Powers (2004.04.05.1508 MST)]
Rick Marken (2004.04.05.1330) --
I don't think the correlations are what we would use to test the models. I
would test the economic models by looking at the correlation between model
behavior and the behavior of real world economic variables that correspond
to model variables.
I agree. The only reason to look for correlations between variables is that
sufficiently high correlations call for an explanation, and a model might
give us that. If prices and inventories are (negatively) correlated, that
could be explained by a model of a typical manager who tries to maintain
inventories at a constant level by adjusting prices. If inventories are
falling, the product is in demand and a higher price can be obtained; if
they are rising, demand has fallen off and having a sale might be prudent.
The only thing that is interesting to me about the
lagged correlations between investment and growth is that they are the
opposite of what one would expect based on the assumption that, on average,
increased investment leads to increased growth.
True. I have often suspected that the myth about investment driving growth
may have something to do with the fact that the first thing an entrepreneur
does after persuading a lot of people to invest their money in his
enterprise is to vote himself a very large salary plus bonuses. In that way
if he happens to lose all that money, at least he comes out a winner (since
the corporation, not he, is liable for blowing all the cash).
I sometimes wonder whether the story of economics, once we get all the
smokescreens out of the way, is not going to turn out to be extremely simple.
Best,
Bill P.
···
The correlations don't say
anything about how investment and growth _are_ related but I think they are
clearly inconsistent with the simple assumption that investment, on average,
leads to growth.
Best
Rick
--
Richard S. Marken
MindReadings.com
Home: 310 474 0313
Cell: 310 729 1400

